Most people have financial goals.
They want to earn more.
Save more.
Invest more.
Pay off debt.
Own property.
Build financial freedom.
But goals alone don’t necessarily create direction.
You can have a long list of financial goals and still feel uncertain about where your money is taking you.
A financial vision goes deeper.
It asks you to imagine the financial life you actually want and then work backwards to determine what needs to happen to create it.
Your financial vision connects today’s decisions with tomorrow’s possibilities.
It gives your money a reason.
And when you have a clear reason, financial planning becomes much more intentional.
What Is a Financial Vision?
A financial vision is a clear picture of the financial future you want to create.
It combines the practical and the personal.
It considers:
- How much you want to earn
- How much you want to save
- What you want to own
- What you want to invest
- How much financial security you want
- What level of financial freedom you want
- How you want to spend your time
This makes it different from a simple financial goal.
A goal might be:
“I want to save £20,000.”
A financial vision might be:
“I want to build enough financial security that unexpected expenses no longer cause me stress and I have the freedom to make decisions from choice rather than financial pressure.”
The goal gives you a number.
The vision gives the number meaning.
Why You Need a Financial Vision
Without a vision, money management can become reactive.
You respond to bills.
You respond to expenses.
You respond to opportunities.
You respond to financial problems.
Your decisions are determined by what is happening now.
A financial vision allows you to start making decisions based on where you want to be.
This changes the question from:
“What should I do with my money?”
to:
“What does my future need me to do with my money today?”
That is a very different mindset.
Your Financial Vision Should Begin With Your Life
Your financial vision shouldn’t begin with a spreadsheet.
It should begin with you.
Before deciding how much money you want, ask yourself what you want your money to support.
Think about:
Your Time
How would you ideally spend your time?
Would you work less?
Work differently?
Build a business?
Have more flexibility?
Take longer breaks?
Your Home
Where would you like to live?
What kind of home would support the life you want?
Would you rather own outright, have a smaller mortgage or have the flexibility to move?
Your Work
Do you want to continue doing the work you currently do?
Would you like to build something of your own?
Would you like multiple sources of income?
Would you like the ability to choose which work you accept?
Your Experiences
What would you like your money to make possible?
Travel?
Learning?
Adventure?
Creativity?
Time with the people you care about?
Your Financial Security
What would make you feel financially secure?
A certain amount of savings?
No consumer debt?
Investment income?
Multiple income sources?
A paid-off home?
There isn’t one correct answer.
Your financial vision should reflect your priorities.
See Your Future Before You Build It
One of the most useful exercises you can do is to imagine an ordinary day in your future financial life.
Not your dream holiday.
Not the moment you become a millionaire.
An ordinary Tuesday.
Imagine waking up five or ten years from now.
Where are you?
What does your morning look like?
What work are you doing?
How much financial pressure are you experiencing?
What happens when an unexpected expense appears?
How do you make financial decisions?
What choices do you have?
What have you built?
How does money feel in your life?
The ordinary details are important.
They help turn an abstract financial ambition into something tangible.
Your vision becomes something you can move towards rather than simply something you hope will happen.
Don’t Build Someone Else’s Financial Future
There is a danger in creating your financial vision from other people’s lives.
Social media makes this particularly easy.
You see:
The house.
The car.
The holidays.
The business.
The investment portfolio.
The lifestyle.
And you assume that is what financial success should look like.
But you don’t know what those things actually cost the person who owns them.
More importantly, you don’t know whether you would even want the life behind the image.
Your financial vision needs to answer:
“What do I want?”
Not:
“What would make other people think I’ve succeeded?”
This distinction can save you years of chasing the wrong things.
Financial Vision vs Financial Goals
Your vision is the bigger picture.
Your goals are the milestones.
For example:
Financial Vision
I want to become financially independent and have greater control over how I spend my time.
Five-Year Goal
Build £250,000 of investments and other productive assets.
One-Year Goal
Invest £25,000 and increase my income.
90-Day Goal
Increase monthly surplus by £500 and establish a consistent investment plan.
This Week
Review my spending and identify £125 of monthly expenditure I can redirect towards my financial goals.
Now you have a connection between the future and today.
Vision.
Destination.
Goals.
Actions.
That is how direction becomes strategy.
Your Financial Vision Should Stretch You
Your vision should feel possible enough to pursue but ambitious enough to require growth.
If your vision is simply a slightly improved version of your current circumstances, you may not be thinking far enough ahead.
Ask:
“If I wasn’t limited by what I currently earn, know or understand, what financial life would I create?”
This doesn’t mean ignoring reality.
It means separating your current position from your ultimate possibility.
Your current income is a fact.
It is not necessarily your permanent income.
Your current savings are a fact.
They are not necessarily your future savings.
Your current financial knowledge is a fact.
It doesn’t have to remain your level of knowledge.
Your financial vision should give you a reason to grow.
Turn Your Vision Into Financial Numbers
Eventually, your vision needs to become measurable.
Consider five numbers.
1. Your Desired Income
What level of income would support the life you want?
2. Your Desired Monthly Surplus
How much would you ideally have available after your essential spending?
3. Your Financial Safety Number
How much would you need in accessible savings to feel financially secure?
4. Your Asset Target
What level of investments or productive assets would help you move towards your destination?
5. Your Freedom Number
What level of income or assets would allow you to make the choices you want?
These numbers don’t need to be perfect.
They can be estimates.
The purpose is to turn an idea into something you can work with.
Let Your Vision Influence Your Financial Decisions
A financial vision becomes valuable when it changes your behaviour.
Suppose your vision is to become financially independent.
You receive an unexpected £2,000.
Without a vision, you might simply spend it.
With a vision, you might ask:
“Which use of this £2,000 moves me closer to the future I’m building?”
Perhaps some goes towards security.
Some towards investing.
Some towards a skill that could increase your income.
Some towards enjoyment.
The point isn’t that every pound must be invested.
The point is that your choices become intentional.
Your Vision Can Change
There is no need to create a financial vision and then become trapped by it.
You will change.
Your circumstances will change.
Your priorities will change.
Your opportunities will change.
Your understanding of money will change.
Your financial vision should therefore be reviewed regularly.
Perhaps once or twice a year, ask:
Is this still the financial future I want?
If it is, continue.
If it isn’t, adjust it.
Changing your destination because you’ve discovered something more meaningful isn’t failure.
It is clarity.
The Week 39 Financial Vision Exercise
Set aside 30 minutes without distractions.
Write at the top of a page:
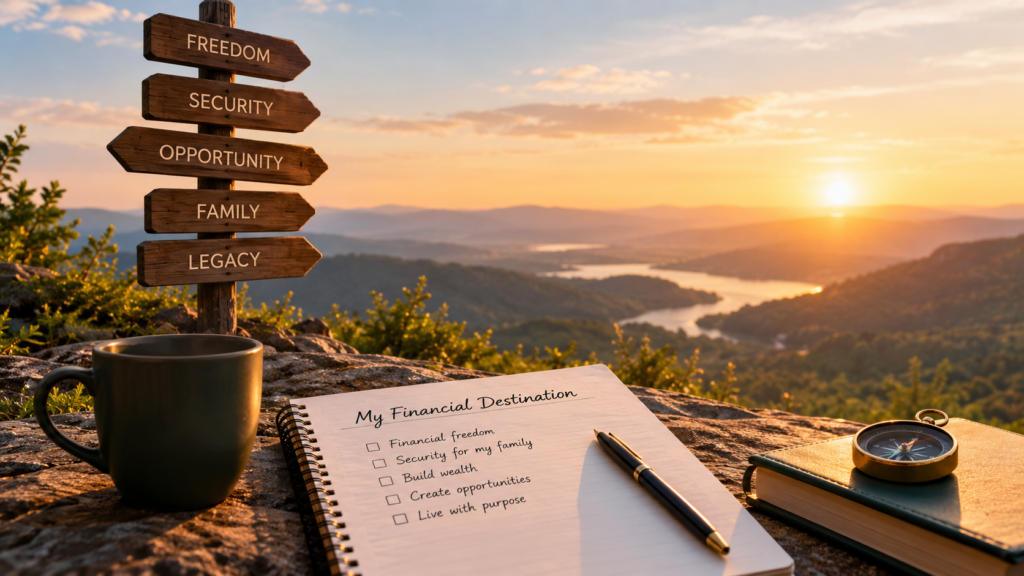
“My Financial Life in Five Years”
Then complete the following.
My income
I would like my income to be approximately:
£________ per year
My monthly financial position
I would like to have approximately:
£________ available after essential spending
My savings
I would like to have:
£________ in accessible savings
My assets
I would like to have built:
£________ in investments/property/business/other productive assets
My freedom
I would feel financially free if:
________________________________
My lifestyle
My money would allow me to:
________________________________
My work
I would like my relationship with work to be:
________________________________
My biggest financial concern today
________________________________
My future financial reality
In five years, I want money to feel:
________________________________
Then bring it all together into one paragraph.
Start with:
“I am building a financial life where…”
Don’t worry about making it perfect.
Make it honest.
From Vision to Strategy
A vision tells you what you want.
A destination tells you where you’re going.
Goals tell you what needs to happen.
But eventually, you need a strategy.
That is where we are heading next.
Because once you know what you’re building, you can begin asking:
“What is the best way for me to get there?”
That means looking honestly at your income, spending, saving, investing, assets, skills and opportunities.
You don’t need somebody else’s financial strategy.
You need one that fits your destination.
The Bigger Lesson
Your financial future is being shaped whether you consciously design it or not.
Every pound you earn.
Every pound you spend.
Every pound you save.
Every investment you make.
Every skill you develop.
Every opportunity you pursue.
Every financial decision you avoid.
They are all contributing to the future you are creating.
The question is whether they are contributing intentionally.
Your financial vision gives you the opportunity to step back and decide:
“This is the future I want to build.”
Then you can begin making today’s decisions from that future.
The Tjintowealth Principle
A financial vision turns money from something you manage into something you intentionally direct.
You don’t need to know exactly how your future will unfold.
You don’t need to predict every market movement.
You don’t need to have all the answers.
But you do need to know what you’re building towards.
Because when the destination becomes clear, the next step becomes easier to see.
See the future.
Define the destination.
Build the financial strategy.
Take the next step.